Regular jumbo loan
- Purchase price
- $1,500,000
- Down payment, 10%
- $150,000
- Monthly mortgage insurance
- None
- Funding fee
- None
$150,000
Cash for the down payment

For veterans, active duty and eligible surviving spouses
Buy with zero down and no monthly mortgage insurance on loans up to $5 million, even when you run your own business.

The problem
Most veterans I talk to think VA is for starter homes. It's not. Where a VA loan really shines is on the bigger purchase, because a jumbo loan on a $1.5 million home is going to want at least 10% down, which is $150,000 out of your pocket before closing costs. With full entitlement VA doesn't have a loan limit (VA.gov), as long as you qualify for the payment and the appraisal comes in at value. Full entitlement just means you've never used your benefit, or you sold the home and paid off the last VA loan, or you had your entitlement restored.
The challenge for my self-employed veterans is the tax returns. Rightfully so, CPAs help their clients take advantage of every deduction to lower their tax liability, but as a loan officer I have to calculate qualifying income off what's actually reported. So a business owner with a great CPA can look like he makes half of what he really makes. VA does let me add depreciation back, which helps, but it won't fix all of it.
The other thing that trips people up is a VA loan they still have. If you kept your last house as a rental, part of your entitlement (your VA benefit) is still tied up in that loan, which is called partial entitlement, and now the county loan limit comes back into play. It doesn't cap your purchase price, but it can mean you'll need some money down on the new one.
On the first call I always run the VA numbers first, because when VA works it's usually the best deal out there. If the returns or the entitlement get in the way, I'll lay out a bank statement loan right next to it so you can see both and decide.
Side by side
On a $1.5 million home, VA usually wins for a veteran with full entitlement, because it asks for $0 down while a jumbo loan asks for at least 10%. The conforming limit, the most Fannie Mae and Freddie Mac will buy, is $832,750 in most counties in 2026, so this price is well into jumbo territory. VA does charge a funding fee, a one-time charge most veterans roll into the loan.
$150,000
Cash for the down payment
$0
Cash for the down payment
VA keeps $150,000 in this veteran’s accounts on the same home.
First use of the VA benefit, home you live in. Closing costs not included.
Self-employed
When your tax returns undersell your business, a bank statement loan can count 12 months of deposits instead of the smaller income your returns show after write-offs.
Choose this if your returns show enough income for the home you want.
Choose this if write-offs shrink your returns too far, and you have the down payment.
Bottom line
I only reach for the bank statement loan when VA can’t count enough of your income. It’s a non-QM (non-traditional) loan, meaning it falls outside the federal “qualified mortgage” rules so it can use deposits instead of tax returns. My bank statement loan page walks through how deposits become income.
Real math
One consultant’s returns are strong enough for VA, a retired officer buys a $2.4 million home with no money down, and a landscaper’s write-offs push him to a bank statement loan, so each one ends up with a different answer.
Scenario 1 · Self-employed, and VA works
He has owned his cybersecurity firm for six years. It’s set up as an S corporation, a type of company where he pays himself a salary and takes the rest as profit.
The numbers
The result
$22,917/mo
Qualifying income from two years of tax returns
VA averages his last two years and adds back the depreciation on his business return, which gives him plenty of income for a $1.2 million home with nothing down.
Watch for: If his second year had come in lower than his first, the lender would want to know why, and might use the lower year.
Scenario 2 · A big home with no money down
He retired after 22 years and now works for a defense company. He has never used his VA benefit, and he has a 30% disability rating.
The numbers
The result
$0 down
Cash for the down payment with full entitlement
Because he has full entitlement, the San Diego County limit of $1,104,000 doesn’t apply to him, and skipping the funding fee keeps $51,600 off his loan.
Watch for: At this size, lenders set their own rules on top of VA’s. Expect a higher credit score, often 700 or more, and some money left in the bank after closing.
Scenario 3 · Write-offs push him off VA
His company deposits close to $2 million a year, but after equipment, trucks and write-offs, his tax returns show $84,000. That’s $7,000 a month, not enough for this home on VA.
The numbers
The result
$80,000/mo
Income from 12 months of bank statements
The expense factor is the share of deposits a lender assumes goes to business costs. Even after counting only half his deposits, he shows more than ten times the income VA could count.
Watch for: He needs 10% down here, where VA would have needed none. Once his tax returns catch up to what the business really earns, a VA cash-out refinance can replace this loan.
Get my options
Three quick taps and an optional note. I read every one myself and get back to you, usually the same day.
What are you looking to do?
How do you earn most of your income?
When would you like to buy or close?
Optional. A sentence or two about your situation helps me come to our call prepared.
Where should I reach you?
Your answers are already filled in below, so I’ll know your situation before we talk.
Rather just talk?
Calculator
With full entitlement you can put $0 down, and the funding fee is 2.15% of the loan the first time you use VA. Enter a price and your entitlement to see your own numbers, and if you still have a VA loan on a home you kept, pick the county.
Down payment
$0
With full entitlement · closing costs not included
Example math from VA's entitlement and funding fee rules for a purchase. Lenders run entitlement math slightly differently, so I check yours on your Certificate of Eligibility. County limits are 2026 one-unit limits from FHFA.
Who this is for
These are the veterans and service members I work with most.
You run a business and your returns are full of write-offs. VA adds depreciation back, and if that’s still not enough, a bank statement loan can count your deposits instead.
You’re buying a home over $1 million and would rather keep your cash working than hand it over as a down payment.
Your military retirement pay and your new salary both count, and so can disability compensation.
You’re moving for new orders and keeping your last home as a rental. Partial entitlement still gets you into the next one, sometimes with a small down payment.
If you receive VA disability compensation, there’s no funding fee. On a $2 million home, that’s $43,000 you don’t pay.
You can use VA while you’re still serving, and your housing allowance can count as income.
If you meet VA’s service requirements, you get the same benefit, with the same funding fee as other veterans.
Eligible surviving spouses can use the benefit, and those who receive Dependency and Indemnity Compensation, the monthly VA payment to survivors, pay no funding fee.
Affordability
VA decides you can afford the payment by looking at two numbers together: your debt-to-income ratio and your residual income, the money left over each month after the house payment (plus VA’s estimate for upkeep and utilities), taxes and your other bills (38 CFR 36.4340). Debt-to-income is your monthly debts, including the new house payment, divided by your monthly income before taxes. VA’s benchmark is 41%, but it isn’t a hard limit.
The residual income minimum depends on your family size and region. For a family of four on a loan of $80,000 or more, it’s $1,003 a month in the South and $1,117 in the West. When your ratio is over 41% and your residual income is at least 20% above that minimum, the lender doesn’t have to write up extra reasons to approve it.
On a big loan with a big income, residual income usually works in your favor, because the leftover money is large even when the payment is too. That’s one reason high earners can do well on VA. Here is the order I check things in.
How I take a VA file from first call to approval
Kept your last home?
Partial entitlement means part of your VA benefit is still tied up in a loan you haven’t paid off. VA figures what you have left as 25% of the county’s one-unit loan limit, minus the entitlement already in use (VA.gov). Multiply what’s left by four, and that’s about the largest loan you can get with $0 down.
Above that, lenders ask for a down payment. Most figure it as 25% of the price minus the entitlement you have left, and some figure it on the loan amount instead, which comes out a little lower. Either way, that down payment is usually much smaller than a regular loan would ask for, and there’s still no monthly mortgage insurance.
One tip: the funding fee drops sharply at 5% down. When VA math lands you just under 5%, rounding up can save you thousands.
Worked example
Her old VA loan started at $300,000, so $75,000 of entitlement is still in use. She’s buying a $700,000 home in Douglas County, where the 2026 limit is $862,500.
The math
The tip
$11,991
Funding fee saved by putting 5% down
At 4.9% down, her fee as a repeat user is 3.3%, about $21,966. At 5% down ($35,000), it drops to 1.5%, about $9,975. That’s $625 more down to save about $11,991.
Watch for: Lenders run entitlement math slightly differently, so I check yours on your Certificate of Eligibility before you make an offer.
Requirements
To get a VA loan, you need a Certificate of Eligibility, a home you’ll live in, steady income (two years if you’re self-employed), a credit score around 620 or higher, and a payment that passes VA’s debt-to-income and residual income tests. Lenders add their own rules on bigger loans, so I match you to the program that fits.
VA funding fee on a purchase, by down payment
Purchase, cash-out refinance and the VA streamline refinance (Interest Rate Reduction Refinance Loan, or IRRRL). One- to four-unit homes you live in. VA loans aren’t for second homes or rentals, but you can keep your old home as a rental with partial entitlement.
Checklist
Who this loan fits
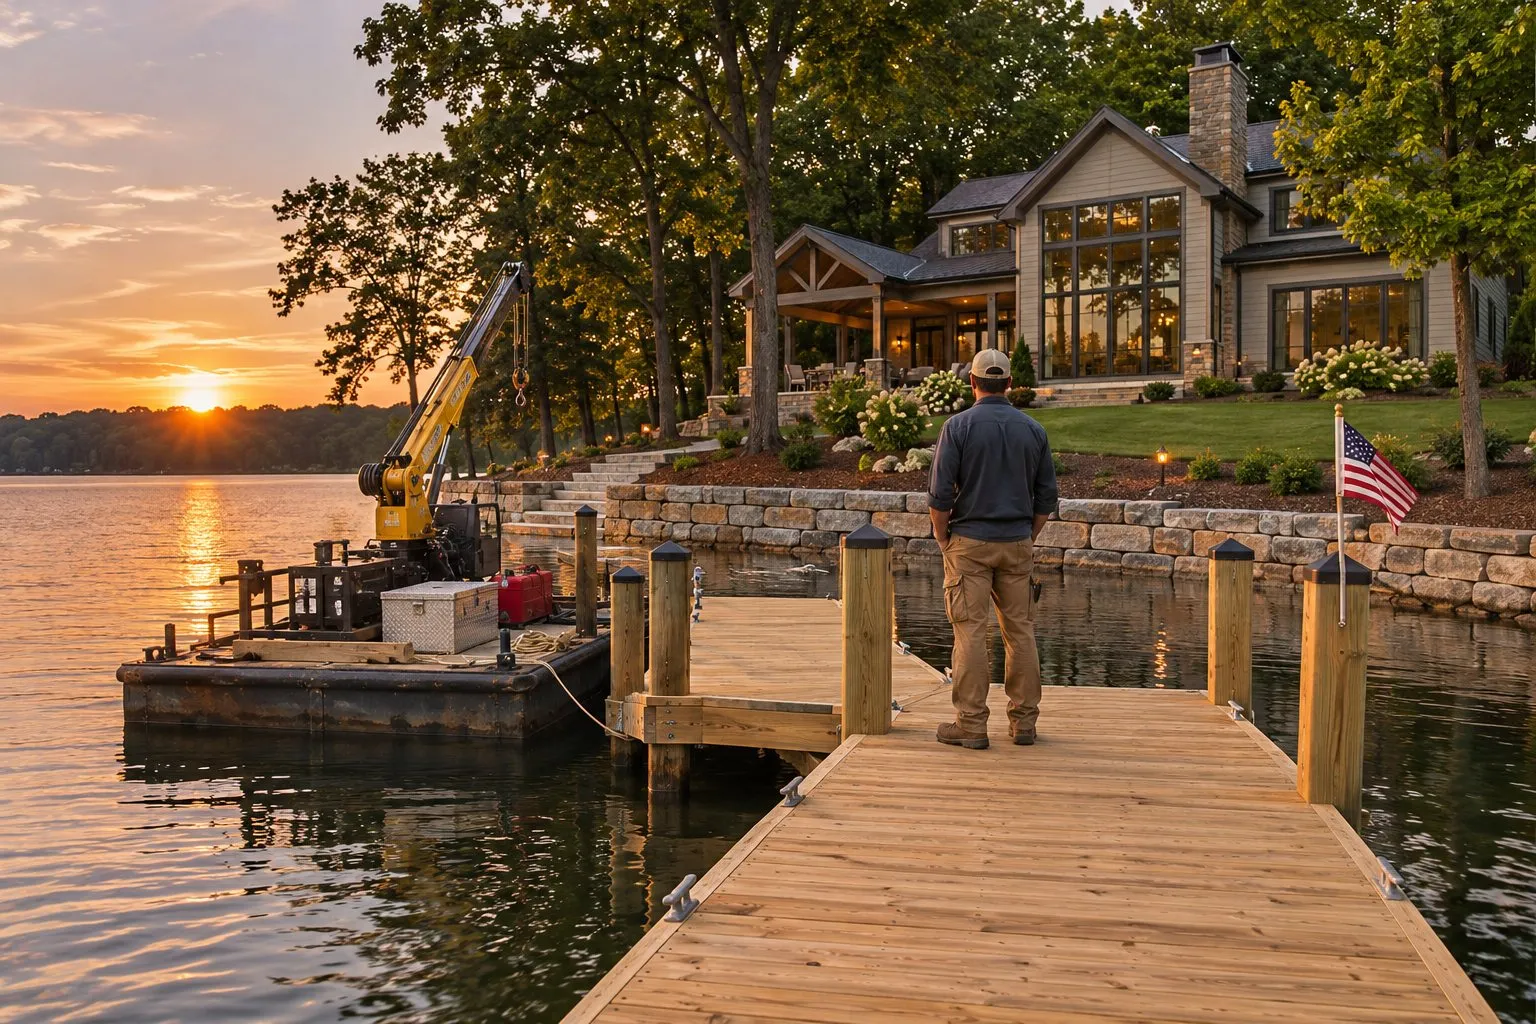
Here's the kind of veteran I see this loan help most. An Army veteran comes home to Lake Norman and spends the next six years building up a company that installs docks and seawalls. Business is good and he's ready to move up to a $1.35 million house on the water.
Like a lot of veterans, he assumes VA is for starter homes, so he's been setting aside $135,000 for a jumbo down payment. He's never used his VA benefit though, which means he could buy this house with zero down and no monthly mortgage insurance.
His tax returns carry a lot of depreciation on the barges, cranes and trucks. VA lets me add that back, and once I do, his two year average is enough to qualify. That $135,000 can stay in the business where he actually needs it.
Watch-outs
There are a handful of things that can cause a VA loan to go sideways as the closing date approaches. Most of them can be fixed, but only if we catch them early.
I always pull the Certificate of Eligibility up front. An old VA loan you forgot about, or one a buyer assumed when you sold, can still be holding part of your entitlement, and you don't want to find that out after you're under contract.
If your returns don't reflect what you really make, I need to know that before you write an offer. Send me your last two years of tax returns first and I'll tell you where you stand.
Most veterans roll the funding fee into the loan, but it still adds to the balance. If you receive VA disability compensation it gets waived, so make sure your lender knows that on day one.
The VA appraiser has to support the price with similar sales, and on a big lakefront or luxury home there may not be many. If it comes in low we can ask for a reconsideration of value, but have some cash set aside just in case.
The building has to be on VA's approved condo list. Let me check it before you write the offer, otherwise the loan can stall while we try to get the building approved.
FAQ
Not if you have full entitlement. VA says borrowers with full entitlement don’t have a loan limit, as long as they can afford the loan and the appraisal supports the price (VA.gov). Lenders still set their own maximum, and the programs I can access go up to $5 million. If you still have a VA loan out there, the county limit comes back into the math, which in 2026 is $832,750 in most counties and up to $1,249,125 in high-cost areas (FHFA).
Yes. VA generally wants two years in business, and one full year can work when you have prior work or training in the same field (VA). The lender averages two years of signed tax returns, plus business returns if you own a corporation or partnership, and adds back depreciation. If write-offs make your income too small, a bank statement loan is the backup plan.
VA itself doesn’t set a minimum credit score. Lenders do, and most of the programs I can access start around 620. On bigger loans, lenders usually ask for more, often 680 to 700 or higher once you’re past about $1.5 million. Your recent payment history matters as much as the score.
On a purchase, it’s 2.15% of the loan the first time you use VA with less than 5% down, and 3.3% after that. With 5% down it’s 1.5%, and with 10% down it’s 1.25%, whether it’s your first use or not (VA.gov). It’s waived if you receive VA disability compensation, and for active-duty service members who’ve received a Purple Heart. Most people roll the fee into the loan. My funding fee guide covers the exemptions.
Yes, if you have entitlement left. You’d keep the first home as a rental and use your remaining, or partial, entitlement on the new one. Depending on the price and the county limit, that can mean a down payment on part of the new loan. My partial entitlement example walks through the math.
No. A VA loan is for a home you live in. You can buy a two- to four-unit property and rent out the other units while you live in one, and you can keep your old home as a rental when you move.
It’s the money left over each month after your house payment (plus VA’s estimate for upkeep and utilities), taxes and other bills. VA sets a minimum by family size and region. For a family of four on a loan of $80,000 or more, it’s $1,003 in the South and Midwest, $1,025 in the Northeast and $1,117 in the West. My post on how hard it is to get a VA loan walks through it.
VA doesn’t require reserves on a one-unit home you live in. On bigger loans, many lenders want some money left in the bank after closing, and if you count rent from the other units on a two- to four-unit property, VA wants you able to cover at least six months of payments without that rent. I tell you the number before you apply.
Yes. If you already have a VA loan, the streamline refinance (IRRRL) can lower your rate with a 0.5% funding fee. A VA cash-out refinance can replace any loan, VA or not, and most programs I can access lend up to 90% of the home’s value. My cash-out refinance page shows how much you can take out.
Google reviews
“Thank you so much for your help in securing my mother’s mortgage loan. I appreciate your professionalism and words of encouragement from your team. You told us what to do, when to do it, and how to do it. I would highly recommend Dale and his team.”
Keep reading
Sources
Program terms are typical ranges across the programs I can access and can change. Not a commitment to lend. Dale Corley, mortgage broker, NMLS #1547543.
Start an application and tell me the price range, whether you’ve used VA before and how you earn your income. I’ll pull your Certificate of Eligibility and show you the VA path and any backup side by side.
Apply Now